The Ultimate Guide to Assumable Mortgages in Nashville, TN
What is an Assumable Mortgage and How Does it Work?
In today’s busy real estate market in Nashville, TN, homebuyers and sellers are always looking for creative financing solutions. One option is an assumable mortgage, also known as a mortgage assumption. This powerful tool lets a buyer take over the seller’s existing loan terms. That includes their current interest rate, repayment period, and remaining principal balance.
Why is this so attractive? Simply put, when current interest rates are higher than those from a few years ago, taking over a lower rate can save you thousands of dollars. That is why, at Lending Hand Mortgage, LLC, we are experts at providing second opinions on assumable mortgages to ensure you are getting the best deal possible in Middle Tennessee.
Not all loans are eligible; however, government-backed loans typically offer this feature. In addition, if you are considering alternatives, you might want to explore a rate and term refinance to see how it compares to a mortgage assumption.
Types of Assumable Mortgages: FHA, VA, and USDA Loans
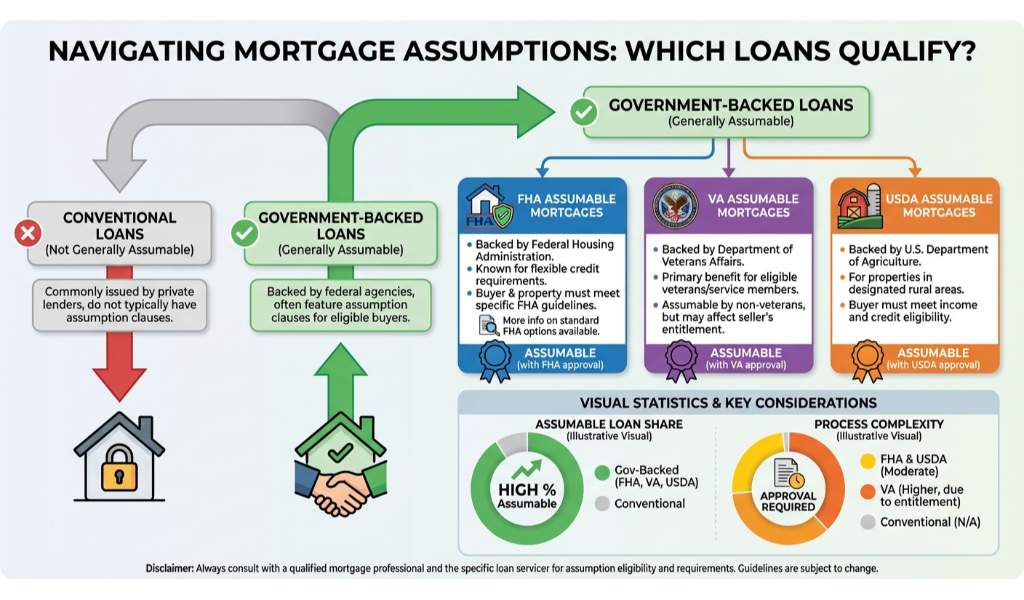
First, it is crucial to understand which loan types qualify for a mortgage assumption. Generally, conventional loans are not assumable, but government-backed loans are. Here is a breakdown of the three main types of assumable mortgage:
- FHA Assumable Mortgages: The Federal Housing Administration backs these loans, and buyers like their flexible credit requirements. Both the buyer and the property must meet specific FHA guidelines. For more details on standard FHA options, visit our FHA purchase loan page.
- VA Assumable Mortgages: Guaranteed by the Department of Veterans Affairs, VA loans offer incredible benefits. A unique feature of a VA assumable mortgage is that the buyer does not need to be a military veteran. However, the seller’s VA entitlement stays tied to the property. The exception is when the buyer is an eligible veteran who substitutes their own entitlement. Learn more about VA benefits in our VA purchase loan guide.
- USDA Assumable Mortgages: Buyers can also assume USDA loans on properties in eligible rural or suburban areas around Nashville. However, these usually require the new borrower to meet strict income limits and property location guidelines.
In short, our team at Lending Hand Mortgage is ready to review your specific scenario. We pride ourselves on lending a hand every step of the way.
| Loan Type | Assumable? | Buyer Requirements | Special Conditions |
|---|---|---|---|
| FHA Loan | Yes | Must meet FHA credit and income standards | Requires FHA lender approval |
| VA Loan | Yes | Must meet VA credit standards | Buyer does not need to be a veteran, but seller entitlement is impacted |
| USDA Loan | Yes | Must meet USDA income and location limits | New rates and terms may apply in some cases |
| Conventional Loan | Rarely | Varies by lender | Usually contains a due-on-sale clause |
Why Get a Second Opinion on Your Mortgage Assumption?
Assuming a mortgage can be a complex process. For example, you may face hidden fees, strict lender requirements, and timeline delays. This is why having a trusted direct lender in your corner is essential. We are experts at providing second opinions on assumable mortgages.
How We Review Your Assumable Mortgage
Suppose a seller’s current lender is dragging their feet or offering confusing terms, Kevin Kenerson and the experienced team at Lending Hand Mortgage, LLC can review the details. We have served homebuyers in Nashville and Middle Tennessee through every market cycle since 2005. As a result, we make sure your mortgage assumption is truly beneficial and that you are not overlooking better financing alternatives.
Whether you need a second opinion or want to explore other home financing solutions, our direct lender structure also allows us to provide streamlined approvals and clear communication. Call us today at (615) 859-5363 to speak with a senior mortgage advisor.
Assumable Mortgage FAQs
Q1: What is an assumable mortgage?
An assumable mortgage allows a homebuyer to take over the seller’s existing home loan. In other words, the buyer keeps the original interest rate, repayment schedule, and loan balance.
Q2: Are all mortgages assumable in Nashville, TN?
No, most conventional loans have a due-on-sale clause, so buyers cannot assume them. However, government-backed loans like FHA, VA, and USDA loans are typically assumable.
Q3: Do I need to qualify to assume a mortgage?
Yes. In fact, the buyer must go through an underwriting process and meet the credit and income requirements of the agency backing the loan.
Q4: Can a non-veteran assume a VA loan?
Yes, a non-veteran can assume a VA loan, but the original veteran seller will not regain their VA loan entitlement until the borrower pays off the assumed loan in full.
Q5: Why should I get a second opinion on a mortgage assumption?
The assumption process can be complicated and sometimes costly. Therefore, getting a second opinion from experts like Lending Hand Mortgage ensures you are making the best financial decision for your unique situation.