Tennessee-First Home Financing: Buying Across Nashville, Middle Tennessee, and Beyond
Lending Hand did not build a Tennessee book of business by pretending every market is the same ZIP code. Madison is home base. Nashville is a flagship search market. Middle Tennessee is where many of our purchase files live. The working strategy – the one we discuss in planning meetings and then execute in content and process – is Tennessee-first: earn authority across the state, then serve the file in front of us with local honesty.
I am Kevin Kenerson with Lending Hand Mortgage, LLC (NMLS #152227), 510 Lentz Dr, Madison, TN. Since 2005 we have helped borrowers with a simple standard: Lending a Hand Every Step of the Way. This guide is for buyers and refinancers who need financing that works in Nashville, Goodlettsville, Hendersonville, Gallatin, Madison, and other Tennessee markets – not a generic national script.
Start the conversation at lhmtg.com or call (615) 390-7534.
What Tennessee-first financing actually means
Tennessee-first is not a slogan. It is a file-building habit:
- Lead with Tennessee market reality on taxes, insurance, and contract timing
- Treat Nashville metro strength as one corridor inside a wider state story
- Build pre-approvals that listing agents in Middle Tennessee can trust
- Keep product choice honest when the borrower is relocating into TN or moving across counties
If your research only says “best mortgage broker near me” and stops at a city name, you still need a statewide-capable process behind the letter.
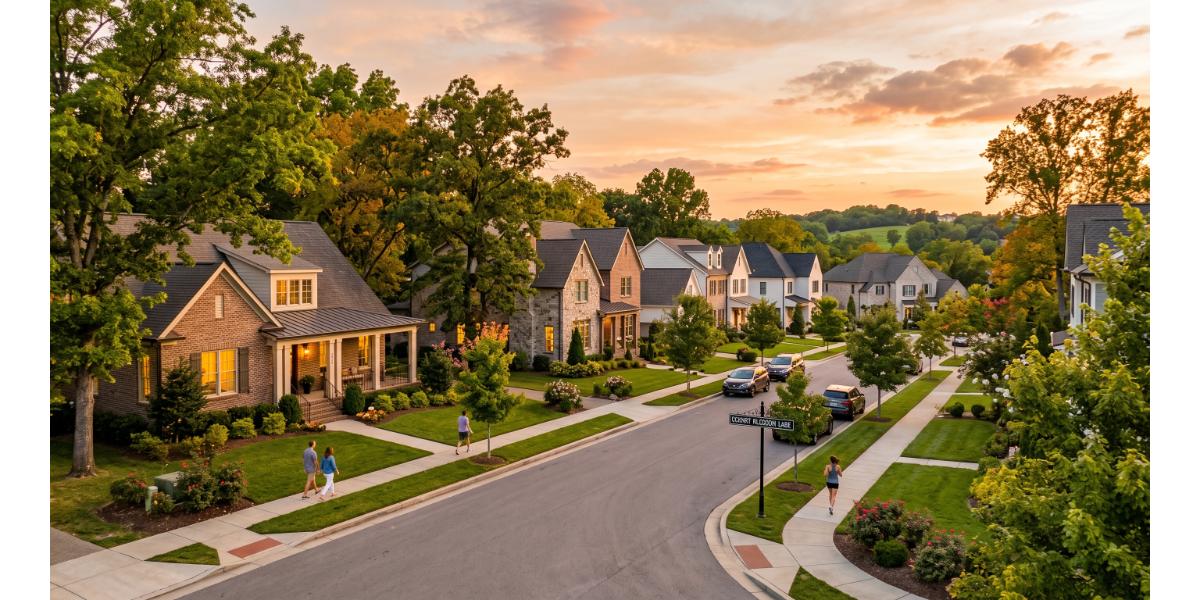
Middle Tennessee corridors we see every week
Purchase files often cluster around:
- Nashville and surrounding in-town neighborhoods where offer competition punishes soft approvals
- Goodlettsville, Madison, and nearby where our Madison headquarters sits close to the work
- Hendersonville and Gallatin where move-up and first-time buyers mix in the same week
- Broader Middle Tennessee where commute, schools, and new construction change the property story
The loan math changes with income type. The local process changes with property type, HOA docs, appraisal expectations, and how fast you can return conditions. Tennessee-first guidance holds both in view.
Relocating into Tennessee: start the file before the house hunt peaks
Borrowers moving into Tennessee from other states often arrive with a partial plan: a rate from an old bank relationship, a maximum price from an online calculator, and a weekend of listing tours. Ready financing looks different:
- Map income documentation that will satisfy a Tennessee underwrite
- Clarify whether conventional, FHA, or VA is the clean lane
- Stress-test payment comfort against Tennessee insurance and tax assumptions
- Decide whether you need a second opinion on an out-of-state quote before you write offers
Waiting until you fall in love with a Hendersonville or East Nashville address is how soft letters become expensive problems.
Contract-ready across county lines
A Tennessee contract-ready borrower can answer the same questions whether the property is in Madison or further across the state:
- Income shape and calculation method
- Debts and credit story with mortgage eyes
- Cash to close and reserves after funding
- Property type risks (condo docs, new construction, unique appraisal)
- Realistic closing timeline with named owners for each bottleneck
Lending Hand’s senior advisors average 10+ years for a reason: pattern recognition travels better than a rate sheet.
Product fit still beats geography theater
Statewide visibility does not mean one product for every household. We still match lanes to files:
- Conventional when credit, down payment, and reserves support it
- FHA when flexibility is the honest path
- VA when entitlement should be used, not abandoned
- Refinance structures when staying in Tennessee and improving payment or cash position is the goal
Tennessee-first content and Tennessee-first advising share the same rule: specificity beats buzzwords.
How we keep borrowers from becoming unpaid project managers
Across Tennessee transactions, the failure mode is usually coordination: appraisal, title, insurance, HOA, and document requests drifting without an owner. Our job is to sequence those pieces so you are not forwarding the same PDF to five inboxes. That operational standard is why so much of our work arrives by referral.
New construction and unique property stories inside Tennessee
Statewide buying is not only existing homes on quiet streets. Tennessee files also include:
- New construction with builder timelines that fight lender conditions
- Condos that need association questionnaires early
- Properties where appraisal comps are thin outside the densest Nashville pockets
- Move-up purchases that depend on a clean sale of the current home
Tennessee-first advising means naming those risks in week one, not after the seller has already accepted your offer.
Refinance while staying in Tennessee
If you are keeping the house and changing the loan, statewide context still matters. Insurance renewals, tax assessments, and title curing behave like local problems even when the rate quote looks national. We review refinance paths the same way we review purchases: payment comfort, product fit, reserves, and a calendar someone owns.
A practical plan if you are buying in Tennessee this season
- Write your payment comfort band and cash-to-close limit before touring.
- Gather income and asset docs into one folder.
- Book a Tennessee-first readiness call at lhmtg.com.
- Leave with a product lane, a gap list, and a letter strategy that matches your market.
- If you already have a bank quote, ask for a second opinion before you rely on it in a multiple-offer fight.
Frequently asked questions
Do you only serve Nashville?
Nashville and Middle Tennessee are core markets, and our planning focus is Tennessee-first statewide. Ask us about your county and property scenario so we can confirm fit and licensing coverage.
I already have a pre-approval from a national bank. Do I need a local team?
You need a team that can underwrite and coordinate on Tennessee timelines. A second look often clarifies whether the national letter is truly contract-ready.
Can you help if I am buying outside Middle Tennessee?
Tell us the market and loan type. We will be direct about what we can support and how the file should be built.
We are a two-income household with overtime and bonuses. Does that change the plan?
Yes. Income shape drives product and documentation. Bring the messy truth early so the Tennessee letter matches the underwrite, not a hopeful calculator.
How do I start?
Visit lhmtg.com, call (615) 390-7534, or use (615) 656-7956. Say whether you are relocating, already shopping, or refinancing in Tennessee.
Kevin Kenerson – Lending Hand Mortgage, LLC – Nashville / Madison, TN – NMLS #152227
Equal Housing Opportunity. Lending Hand Mortgage, LLC. NMLS #152227. Licensed where we operate; ask us about your state and property scenario.