Why the Person Guiding Your Home Financing Matters as Much as the Numbers
In Nashville and across Middle Tennessee, buyers obsess over rate screenshots for a reason: the monthly number feels concrete. The person guiding the file feels softer, so it gets treated like a nice-to-have. That is backwards. The same rate on two different desks can produce two different outcomes once appraisal conditions, income calculation, title timing, and underwriting overlays enter the room.
I am Kevin Kenerson with Lending Hand Mortgage, LLC (NMLS #152227). We are a Nashville-area mortgage team founded in 2005 in Goodlettsville and based at 510 Lentz Dr in Madison, TN. Our philosophy is simple: Lending a Hand Every Step of the Way. Most of our work arrives by referral because borrowers remember how the process felt when something unexpected showed up. This article explains why the guide matters as much as the quote, and how to evaluate that guide before you lean on a letter in a competitive offer.
If you already have a bank quote or a soft approval, bring it to lhmtg.com or call (615) 390-7534 for a second look. Clarity beats hope.
Numbers without a guide are an incomplete map
A rate and a payment estimate answer one question: what might the loan cost if every assumption holds. Real Middle Tennessee files break assumptions. Overtime gets averaged differently than a borrower expected. A condo questionnaire arrives late. An appraisal comes in thin on a unique Gallatin or East Nashville property. Gift funds need a cleaner trail. Insurance quotes jump after the binder request.
When those moments hit, the spreadsheet does not talk to the listing agent, the underwriter, or the title company. A person does. The quality of that person shows up as:
- How early problems are named
- How cleanly options are explained without panic language
- How fast conditions move once they appear
- Whether you still understand your file on closing week
Borrowers who only shop the number often discover too late that they bought a quote without buying a process.
Clarity from the first conversation: what strong guidance sounds like
A capable home financing advisor does not impress you with jargon. They reduce fog. In a Lending Hand first meeting, clarity usually means you leave knowing:
- Which loan lane fits your income and credit story today
- Which documents still block a contract-ready letter
- What payment band matches both approval math and household comfort
- Which risks are worth watching for your property type and timeline
- Who owns each next step on our side and yours
If a first call only produces a maximum purchase price and a smile, you do not yet have guidance. You have a marketing number.
Timelines are a people problem before they are a calendar problem
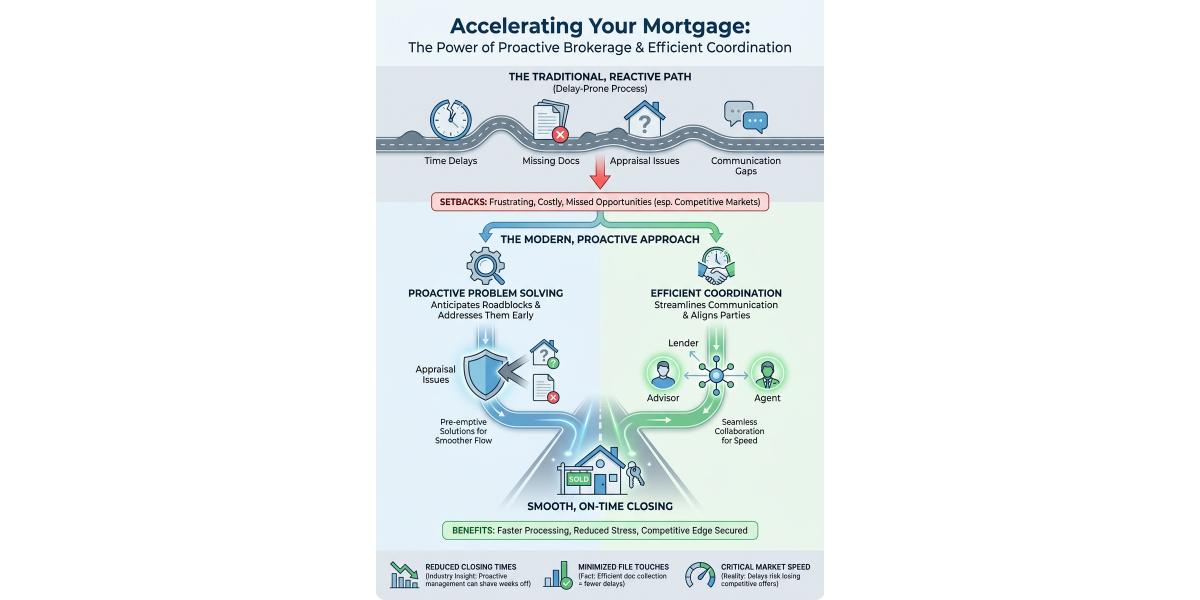
Middle Tennessee contracts punish slow coordination. Appraisal orders, conditional underwriting, insurance binders, HOA docs, and wire instructions all have owners. When your advisor is reactive, those owners operate in parallel silence until something breaks. When your advisor is proactive, the file has a sequence.
Practical signs your guide is protecting the calendar:
- Document requests arrive in batches with priorities, not as random daily surprises
- Appraisal and title are tracked against contract dates, not “whenever the vendor replies”
- Conditions are translated into plain English with a clear “done when” definition
- Your agent gets updates before they have to chase you for status theater
Lending Hand’s senior advisors average over a decade in this work for a reason: pattern recognition shortens the distance between “condition issued” and “condition cleared.”
Confidence is built by honest tradeoffs, not cheerleading
Confidence is not the feeling that nothing will go wrong. Confidence is knowing what happens if something does. A strong guide will tell you when a conventional path is cleaner than stretching for a headline payment, when waiting two weeks to clean revolving utilization is smarter than forcing a letter today, or when a VA structure deserves a second look before you abandon entitlement benefits.
That honesty is especially valuable in Nashville’s mixed market: first-time buyers in Madison and Goodlettsville, move-up households in Hendersonville and Gallatin, veterans using VA benefits, and self-employed borrowers whose income needs a careful read. One script does not serve all of them. A guide who listens will change the plan when the facts change.
Rate shopping vs process shopping: how to compare without getting played
You should compare pricing. You should also compare process. When you evaluate Lending Hand against another desk, ask the same questions of both:
- Who underwrites and who closes, and how many hands does the file pass through?
- What conditions typically appear on files like mine?
- How do you handle appraisal gaps or condo questionnaire delays?
- Who is my direct contact after the application, and how fast do they reply?
- What does the letter in my hand actually mean for a Nashville multiple-offer scenario?
A slightly higher quoted rate with a tighter process can still be the cheaper life outcome if it protects your earnest money and your closing date. A rock-bottom screenshot with a missing process can become the most expensive line item on the transaction.
What “direct” control of the file actually changes for borrowers
Borrowers feel the difference when their advisor can drive coordination instead of forwarding hope into a black box. At Lending Hand, we structure purchase and refinance work so the borrower is not the unpaid project manager of five vendors. That shows up as fewer duplicate document asks, earlier escalation when an appraisal or title item stalls, and clearer ownership when a condition needs a phone call instead of another email chain.
If you have ever watched a closing date slip because nobody owned the bottleneck, you already understand why the guide matters as much as the APR.
Second opinions: when bringing another set of eyes is the smart move
You do not need to start over to get better guidance. Common second-opinion moments we see in Middle Tennessee:
- You have a bank pre-approval but do not understand the conditions
- You are under contract and updates feel late or vague
- Your self-employment or VA story was waved through without detail
- The payment quote ignored insurance and tax reality for the property
- You want a refinance review but only received a “rates are rates” shrug
Bring the paperwork you already have. A useful second opinion names what is solid, what is risky, and what should change before you rely on the current path.
How to choose a Nashville home financing guide in one meeting
Use the first conversation as an audition. You are hiring judgment. Listen for:
- Specific questions about your income shape and timeline, not only your dream payment
- Local fluency with Middle Tennessee property and contract patterns
- Willingness to say “not yet” when a letter would be soft
- A clear next-step list you could explain to a spouse or partner
- Compliance clarity, including company identity and NMLS transparency
If you leave more confused than you arrived, that is data. The guide failed the first job: making the map readable.
Frequently asked questions
Is the lowest rate always the right choice?
Not if the file attached to that rate cannot clear conditions on time, or if the product structure fits poorly. Compare total cost, timeline risk, and advisor access together.
Can a good advisor fix a weak credit or document story?
They can design a path, sequence the work, and stop you from making the file worse. They cannot invent eligibility. Early honesty is what makes guidance useful.
Do refinance borrowers need the same kind of guide?
Yes. Rate-and-term, cash-out, and VA streamline decisions still live or die on calculation accuracy, title timing, and clear communication. The house is the same. The judgment still matters.
How do I start with Lending Hand Mortgage?
Go to lhmtg.com, call (615) 390-7534, or reach us at (615) 656-7956. Tell us whether you are shopping, under contract, or asking for a second opinion. We will walk the next steps with you.
Kevin Kenerson – Lending Hand Mortgage, LLC – Nashville / Madison, TN – NMLS #152227
Equal Housing Opportunity. Lending Hand Mortgage, LLC. NMLS #152227. Licensed where we operate; ask us about your state and property scenario.